

Bank CEO KPIs must ensure fair, objective assessment
Bangladesh Bank’s initiative to introduce key performance indicators (KPIs) for evaluating the CEOs of commercial banks is a timely move. At a time when Bangladesh’s banking sector is facing pressure on asset quality, liquidity, profitability, governance and public confidence, a more structured approach to leadership performance deserves serious attention.
But there is a fundamental question worth asking: do bank CEOs really operate without KPIs? Clearly, they do not.
A bank CEO is already judged by numerous financial, operational and regulatory indicators, including profitability, loan growth, recovery, non-performing loans, capital adequacy, liquidity, deposit mobilisation, cost efficiency, compliance, digital transformation and customer service.
In a volatile, uncertain, complex and ambiguous economic environment such as Bangladesh’s, managing these competing priorities is itself a demanding performance exercise. Therefore, the real issue is not whether CEOs have KPIs. The real issue is whether there is an objective, transparent and professional system through which their performance is discussed and assessed by the board.
Performance should be reviewed periodically and supported by evidence, rather than assessed retrospectively through general impressions. The process must be unbiased and consistently applied.
That distinction matters. Banking performance cannot be measured simply by annual profit or business growth. A CEO can generate rapid loan growth, for example, but if asset quality subsequently deteriorates, the apparent success may become a serious institutional weakness.
Similarly, a conservative CEO may deliver modest short-term growth while strengthening risk management, governance and the bank’s long-term resilience.
A meaningful KPI framework should therefore balance growth with risk, profitability with sustainability, and business expansion with governance.
It should also recognise factors outside a CEO’s direct control. Interest rates, exchange-rate movements, inflation, regulatory changes, liquidity conditions and broader economic shocks can significantly influence banking performance.
A fair assessment must distinguish between what management can control and what it cannot. The success of any KPI framework will ultimately depend on the quality of board-level evaluation.
KPIs should be agreed in advance, clearly defined, measurable and appropriately weighted. Performance should be reviewed periodically and supported by evidence, rather than assessed retrospectively through general impressions.
Most importantly, the process must be unbiased and consistently applied. A CEO should not be unfairly penalised for circumstances beyond his or her control. Equally, strong personal relationships should never become a substitute for professional assessment.
This is where a formal KPI framework can be valuable. It can give boards a stronger basis for evaluating management while giving CEOs clarity about what is expected of them.
There is also a danger of turning KPIs into a mechanical scorecard.
Leadership cannot be reduced entirely to numbers. Integrity, strategic thinking, crisis management, succession planning, employee development, organisational culture and institutional reputation also matter. The objective, therefore, should not be judgment-free leadership, but evidence-based judgment.
If implemented properly, Bangladesh Bank’s initiative could gradually establish a stronger performance culture across the banking sector. It could help recognise high-performing CEOs, identify weaknesses earlier and provide future banking leaders with a clearer understanding of what professional excellence means.
Ultimately, this initiative should not be about deciding whether a particular CEO is good or bad. It should be about creating a system where performance is clearly defined, fairly measured, objectively discussed and professionally acted upon.
That would strengthen not only CEOs and boards, but the credibility and resilience of Bangladesh’s banking sector itself.
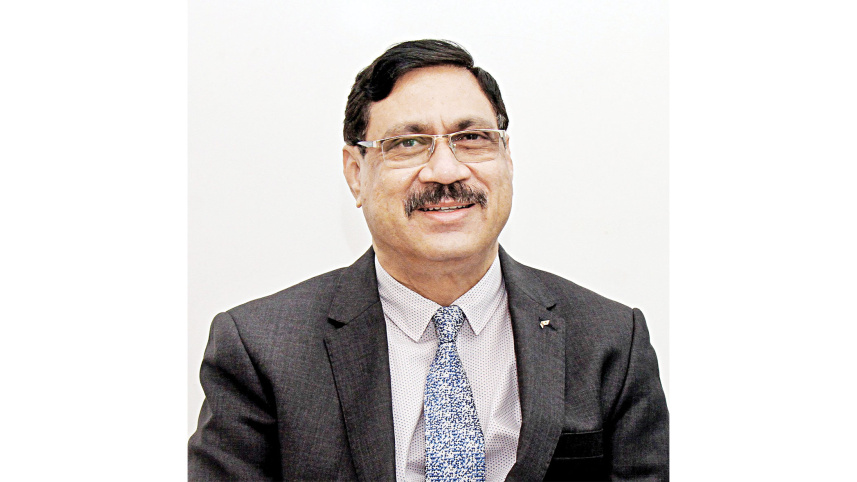
The writer is a former president of FICCI and AmCham Bangladesh
 For all latest news, follow The Daily Star's Google News channel.
Comments