


Banks born of political favour now drowning in bad debt
Three of the nine banks that entered the market in 2013 after receiving licences from the then Awami League government are now weighed down by non-performing loans (NPLs), according to Bangladesh Bank data and audited financial statements.
Of the remaining six, two have double -digit NPLs, while three have NPL ratios above the tolerable threshold.
At the time the licences were granted, there were allegations that political considerations, rather than financial merit, had influenced the decision. Economists say approving banks on political grounds rather than financial need has contributed to the sector’s current woes.
The nine new-generation lenders are Padma Bank, NRB Commercial Bank, NRB Bank, Global Islami Bank, Union Bank, Modhumoti Bank, Midland Bank, Meghna Bank and South Bangla Agriculture & Commerce (SBAC) Bank.
Global Islami Bank and Union Bank have since been folded into Sammilito Islami Bank, along with four other troubled lenders. Their deteriorating financial health came to light after the 2024 political changeover exposed bad loans that had long been concealed.
Both banks were controlled by the controversial S Alam Group and, by the time of the merger, Tk 97 of every Tk 100 they had lent had gone bad.
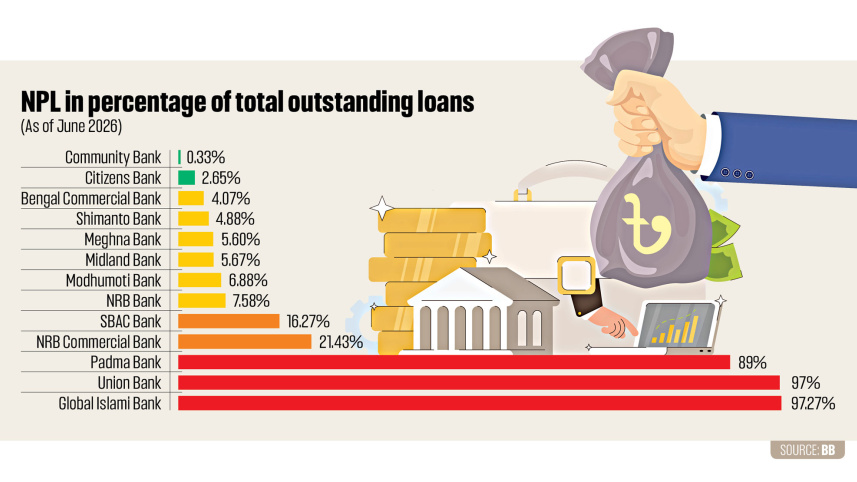
Union Bank made a profit of Tk 160 crore in 2023, then posted a loss of Tk 25,790 crore in 2024. By June this year, its non-performing loans reached Tk 27,134 crore, or 97 percent of total lending.
Global Islami Bank posted a profit of Tk 128 crore in 2023. The following year, it recorded a loss of Tk 1,246 crore. Its bad loans jumped from Tk 221 crore to Tk 12,661 crore in 2024 and stood at Tk 14,219 crore, or 97.27 percent of total loans, by June this year.
Padma Bank is in almost as dire a state, having struggled for years to return money to depositors. By June, its bad loans had reached Tk 4,933 crore, or 89 percent of its loan book.
It has not published accounts for a couple of years, and the Bangladesh Bank (BB) is now considering a merger.
NRB Commercial Bank and SBAC Bank are in less critical but still dangerous territory, with bad loan ratios of 21 percent and 16 percent respectively.
NRB Bank, Modhumoti Bank and Meghna Bank all have single-digit bad loan ratios, but each is above the 5 percent ceiling that regulators generally regard as safe.
Midland Bank stands out as the exception.
It has remained profitable while its bad loans increased only slightly, from Tk 182 crore in 2023 to Tk 189 crore in 2025. But asset quality deteriorated in the first half of 2026, with bad loans reaching Tk 412 crore, or 5.67 percent of total loans, by June.
THE WALKING WOUNDED
Of the nine commercial lenders, SBAC Bank and NRB Commercial Bank have double-digit NPL ratios as their profits have fallen in recent years.
SBAC Bank’s profit fell from Tk 54 crore in 2023 to just Tk 70 lakh in 2025, while bad loans surged from Tk 460 crore to Tk 1,724 crore.
By June this year, bad loans stood at Tk 1,557.27 crore, or 16.27 percent of total loans.
NRB Commercial Bank has followed a similar trajectory. Its profit fell from Tk 198 crore in 2023 to just Tk 7 crore in 2024, before recovering to Tk 13 crore in 2025.
Over the same period, bad loans climbed from Tk 615 crore to Tk 2,524 crore. By June this year, they had risen further to Tk 3,218.78 crore, or 21.43 percent of total loans.
 For all latest news, follow The Daily Star's Google News channel.
“We are now busy reducing our bad loans,” said Md Touhidul Alam Khan, the bank’s managing director and chief executive officer.
He said that before he joined, NRB Commercial Bank’s provision shortfall stood at Tk 3,600 crore, which has since fallen to Tk 802 crore.
The bank aims to bring bad loans below 20 percent, Touhidul said, adding, “We are trying to reduce the bad loans through the one-time exit policy, easy loan rescheduling and other policy support introduced by the banking regulator.”
STILL ABOVE THE SAFE THRESHOLD
NPL levels at NRB Bank, Meghna Bank and Modhumoti Bank are in single digits but are above the 5 percent level considered safe.
Bad loans at NRB Bank climbed from Tk 255 crore in 2023 to Tk 749 crore in 2024, before easing to Tk 593 crore in 2025 and Tk 585 crore, or 7.58 percent of total loans, by June this year.
Tarek Reaz Khan, managing director and chief executive officer of NRB Bank, said the bank has recovered a significant share of its bad loans through BB’s policy support and legal action.
By August this year, the bad loan ratio had fallen further to 7.40 percent, with a target of 5 percent by year-end. “NRB Bank now has strong liquidity,” Tarek added.
Over the past three years, Meghna Bank has expanded rapidly, with both loans and deposits increasing.
But its profit has slumped from Tk 77 crore in 2023 to just Tk 5 crore in 2025. During the same period, its bad loans rose.
By the end of June this year, its bad loans rose further to Tk 432.87 crore, or 5.60 percent of total loans, according to BB data.
Similarly, Modhumoti Bank’s profit fell from Tk 125 crore in 2024 to just Tk 6 crore in 2025, while bad loans reached Tk 561 crore by June, or 6.88 percent of total loans.
A SECOND ROUND, THE SAME STORY
A second round of bank approvals by the Awami League government followed in late 2018 and 2019, bringing Community Bank, Bengal Commercial Bank, Citizens Bank and Shimanto Bank to the market.
Among them, Community Bank is in the strongest position. Its profit rose from Tk 71 crore in 2024 to Tk 102 crore in 2025, while its bad loans had fallen by June to just Tk 5.32 crore, or 0.33 percent of total loans.
Citizens Bank, established in 2020, has also kept bad loans low while expanding quickly, although its profit was just Tk 2 crore in 2025. Its NPLs stood at Tk 162.46 crore, or 2.65 percent of total loans, by June this year.
Bengal Commercial Bank’s profit fell last year, but its deposits and loans grew strongly.
“As a new bank, the overall performance of Bengal Commercial Bank is not bad,” said its managing director, KM Awlad Hossain.
“Some loans were turning overdue because of the wider business climate. We are focusing on loan recovery through different methods, including loan rescheduling and cash recovery,” he told The Daily Star.
Meanwhile, Shimanto Bank’s financial performance has also deteriorated.
Its profit rose from Tk 24 crore in 2023 to Tk 39 crore in 2024, then swung to a loss of Tk 82 crore in 2025 as bad loans jumped from Tk 11.68 crore to Tk 151 crore. By June this year, they had eased slightly to Tk 133.73 crore, or 4.88 percent of total loans.
Banks approved in 2013, and those approved later should not be compared directly because newer banks generally face fewer asset-quality problems in their initial years of operation.
POLITICAL PRICE
Mustafa K Mujeri, executive director of the Institute for Inclusive Finance and Development and a former chief economist of BB, said the country is now seeing the results of banks that were approved because of political considerations.
He said the approval of financial institutions and the appointment of their officials should rest on financial rather than political grounds.
“If that happens, then we can see good results,” he said, adding that the then finance minister had himself acknowledged the banks got licences on political considerations.
“If you take any policy based on political considerations, then you must fail, or there will be no good results,” he told The Daily Star.
“Not only those banks, but the country’s banking sector as a whole is now struggling due to political influence. We should come out of such practices; otherwise the banking sector will not recover soon,” the economist added.
Comments