


Aligning Credit Flow with Seasonal Rhythm and Value-Chain Growth
Financing must move in line with the seasonal rhythm of agricultural activities, turning one loan into ripple effects of productive growth across the rural community.
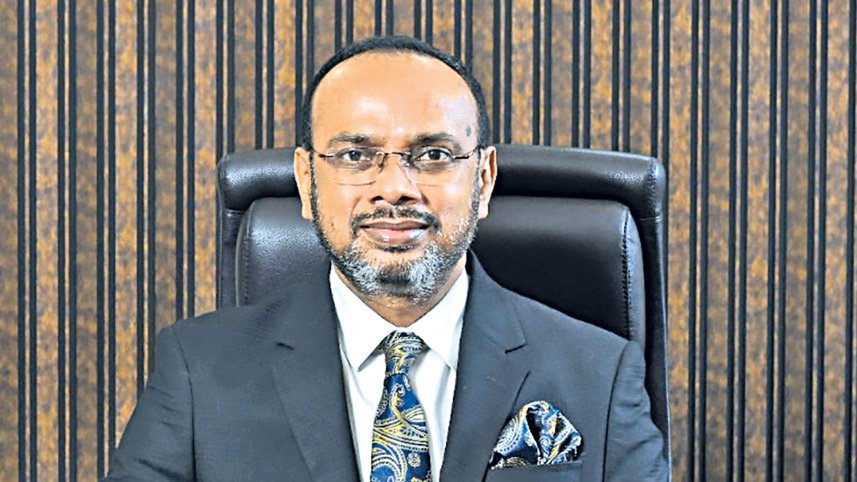
South Bangla Agriculture and Commerce (SBAC) Bank PLC focuses on agriculture, agro-processing, and CMSMEs as central pillars for rural employment and growth. S.M. Mainul Kabir, Managing Director & CEO of SBAC Bank, discusses how aligning loan disbursement with seasonal farming rhythms and expanding agent banking transforms single loans into economic multipliers.
The Daily Star (TDS): How has the agricultural financing landscape in Bangladesh evolved in recent years, and which emerging trends do you consider most significant?
S .M. Mainul Kabir: Agricultural financing is moving toward a value-chain approach extending beyond crop lending into mechanization, fisheries, livestock, cold storage, processing, and marketing. Supported by central bank credit programs, SBAC Bank places agriculture and CMSMEs at the center of our strategy.
TDS: What changes are you seeing in the financing needs across the agricultural value chain?
SMMK: Financing needs have diversified significantly. Farmers require funding for machinery and storage alongside inputs, while agribusinesses need capital for procurement, processing, packaging, and logistics. Credit must align with seasonal farming rhythms and match borrower repayment capacity.
TDS: How is SBAC Bank adapting its agricultural finance products to serve activities beyond crop production?
SMMK: Our financing spans working capital, machinery acquisition, and business expansion across fisheries, livestock, processing, storage, and transport. Central bank refinancing schemes play a key role by keeping credit affordable for rural entrepreneurs.
TDS: Access to formal credit remains difficult for small farmers. What are the principal barriers, and how can banks address them?
SMMK: Inadequate collateral, limited documentation, seasonal income, and physical distance are major hurdles. We address these through simplified procedures, financial literacy, agent banking, and customized repayment schedules while evaluating business viability and cash flows.
TDS: How are agent banking, digital platforms, and new credit assessment methods changing rural finance?
SMMK: Agent banking and digital tools eliminate long-distance travel for farmers and broaden formal access. Alternative transaction data improves credit evaluation, paired with field verification and sound banking judgment.
TDS: With agriculture exposed to climate and market risks, how should financing models evolve?
SMMK: Financing models must reflect climate risks, price fluctuations, and seasonal cash flows. SBAC Bank supports resilience by funding efficient irrigation, modern equipment, and processing infrastructure alongside government risk-mitigation frameworks.
TDS: What more can financial institutions do to support women, young agripreneurs, and small enterprises?
SMMK: Banks can empower young agripreneurs and women through accessible credit, financial literacy, and market connectivity. Financing a small rural food processing enterprise enables it to purchase machinery, buy produce from nearby farmers, and create local jobs.
TDS: Looking ahead, what policy support, institutional changes, or partnerships will be necessary?
SMMK: Achieving the central bank’s Tk 60,000 crore credit target requires sustained refinancing, improved rural infrastructure, reliable credit databases, and deeper partnerships with cooperatives, aggregators, and tech providers.
 For all latest news, follow The Daily Star's Google News channel.
Comments