


Transforming Isolated Credit into Fit-for-Purpose Value-Chain Architecture
Agricultural finance must evolve from isolated lending transactions into an integrated financing ecosystem that supports the seamless flow of capital from seed to shelf.
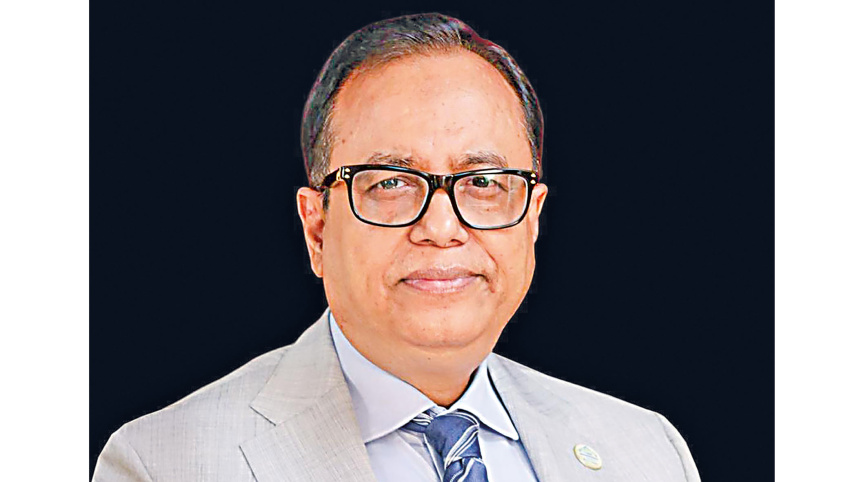
Mercantile Bank PLC is transitioning from conventional production lending toward a cash-flow-oriented value-chain framework supporting post-harvest storage, agro-processing, and green rural enterprises. Mati Ul Hasan, Managing Director of Mercantile Bank, highlights specialized initiatives like ANANNYA and UDAYAN designed to foster women and youth entrepreneurship across Bangladesh’s expanding agricultural economy.
The Daily Star (TDS): How has the agricultural financing landscape in Bangladesh evolved in recent years, and which emerging trends do you consider most significant?
Mati Ul Hasan: The agricultural financing landscape has transitioned from production-focused lending to an integrated value-chain paradigm. Crucial emerging trends driving this transformation include digital financial services, value-chain financing, climate-resilient farming, financial inclusion, and data-enabled credit assessment across rural networks.
TDS: What changes are you seeing in the financing needs across the agricultural value chain?
MUH: Farm-level demand is expanding into machinery, irrigation, livestock, and climate-resilient practices. Agribusinesses require working capital for procurement, aggregation, and transport, alongside term loans for processing plants and cold storage facilities.
TDS: How is Mercantile Bank adapting its agricultural finance products beyond crop production?
MUH: Our lending covers fisheries, poultry, dairy, farm machinery, rural transport, and sustainable green enterprises. We focus on fit-for-purpose financing aligned with the productive cycle, cash flow, and risk profile of each value-chain segment.
TDS: Access to formal credit remains difficult for small farmers. What are the principal barriers, and how can banks address them?
MUH: Constraints include limited collateral, informal operations, low financial literacy, and seasonal cash flows. Agent banking, simplified documentation, and cash-flow underwriting improve credit access while maintaining rigorous due diligence and portfolio quality.
TDS: How are agent banking, digital platforms, and new credit assessment methods changing rural finance?
MUH: Agent banking and digital platforms eliminate geographical barriers, streamline onboarding, and lower operational costs. Transaction histories and digital payment data provide a nuanced credit assessment for borrowers with limited formal documentation.
TDS: With agriculture exposed to climate and market risks, how should financing models evolve?
MUH: Lending must adopt a resilience-oriented framework directing capital to climate-smart irrigation, renewable energy, and modern storage, coupled with credit guarantees, agricultural insurance, and climate-responsive repayment structures.
TDS: What more can financial institutions do to support women, young agripreneurs, and small enterprises?
MUH: Through dedicated CMSME platforms like ANANNYA for women and UDAYAN for youth, Mercantile Bank evaluates business model viability, technical competence, and cash flows over traditional security, generating strong local economic multipliers.
TDS: Looking ahead, what policy support, institutional changes, or partnerships will be necessary?
MUH: A coordinated ecosystem is essential—linking Bangladesh Bank, commercial banks, fintechs, agribusinesses, and insurers around credit guarantees, digital inclusion, and market-linkage infrastructure to finance the entire value chain from seed to shelf.
 For all latest news, follow The Daily Star's Google News channel.
Comments