


Driving Inclusive Growth and Youth Entrepreneurship Across Rural Value Chains
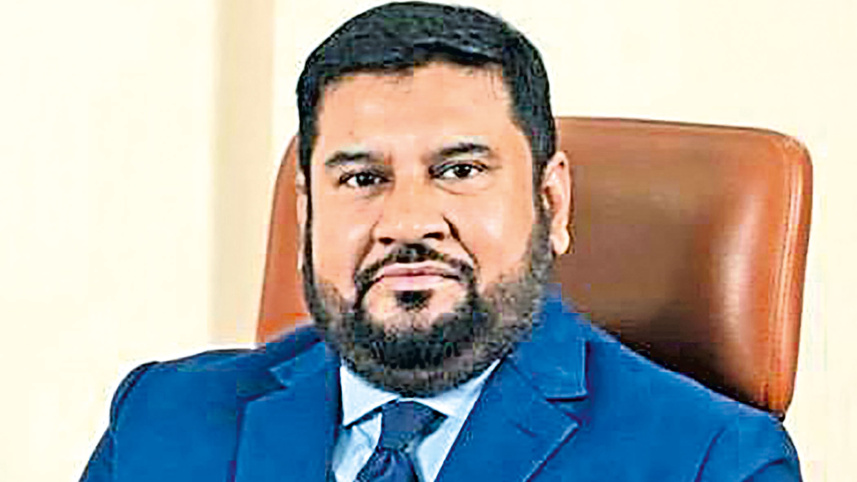
Reaching 142% of our credit target reflects our commitment to anchoring agricultural loans in actual business cash flows rather than land ownership.
NCC Bank PLC achieved an outstanding 142% of its central bank agricultural credit disbursement target by expanding financing across crop cultivation, mechanization, cold storage, livestock, and rural trade. The Managing Director of NCC Bank PLC, M. Shamsul Arefin, outlines how digital banking platforms like ‘NCC Always’ and QR payments enable data-driven credit assessment and foster youth-led agri-entrepreneurship across Bangladesh.
The Daily Star (TDS): How has the agricultural financing landscape in Bangladesh evolved in recent years, and which emerging trends do you consider most significant?
M. Shamsul Arefin: Agricultural financing has transformed from seasonal crop lending into an integrated value-chain model. Key driving forces include digital financial services, agent banking, financial inclusion for women and youth, climate resilience, and data-driven credit scoring across rural communities.
TDS: What changes are you seeing in the financing needs across the agricultural value chain?
MSA: Needs are diversifying rapidly. Farmers require funding for machinery and storage to overcome labor shortages, while agribusinesses need working capital for procurement, processing, packaging, and logistics. Flexible repayment structures must align with seasonal cash flows.
TDS: How is NCC Bank adapting its agricultural finance products beyond crop production?
MSA: We view agriculture as a complete value chain. Our products support feed, machinery, cold storage, packaging, transport, and agri-trading. Reaching 142% of our disbursement target last fiscal year reflects our commitment to anchoring credit in cash flows rather than land ownership.
TDS: Access to formal credit remains difficult for small farmers. What are the principal barriers, and how can banks address them?
MSA: Barriers include sparse documentation, lack of credit history, distance, and seasonal volatility. We address these by simplifying applications, expanding agent banking, promoting financial literacy, and adopting cash-flow-based risk assessment.
TDS: How are agent banking, digital platforms, and new credit assessment methods changing rural finance?
MSA: Digital platforms and agent banking reduce geographic barriers and lower transaction costs. Initiatives like ‘NCC Always’ and QR payments build verifiable digital footprints that inform responsible credit evaluation.
TDS: With agriculture exposed to climate and market risks, how should financing models evolve?
MSA: Financing must promote climate-resilient investments in efficient irrigation, water management, and renewable energy, backed by flexible repayment options during disruptions and stronger insurance linkages.
TDS: What more can financial institutions do to support women, young agripreneurs, and small enterprises?
MSA: Banks must combine credit with knowledge and market access. Through nationwide initiatives like our ‘Entrepreneurship Development & Green Banking’ training, NCC Bank builds skills for women and young agripreneurs driving agritech and logistics.
TDS: Looking ahead, what policy support, institutional changes, or partnerships will be necessary?
MSA: Sustainable progress requires credit guarantees, agricultural risk insurance, digital data sharing, and value-chain partnerships among banks, agribusinesses, and tech providers to establish an inclusive, climate-conscious, and commercially viable agri-finance ecosystem.
 For all latest news, follow The Daily Star's Google News channel.
Comments