


Harnessing digital velocity and soft loans for sustainable farming
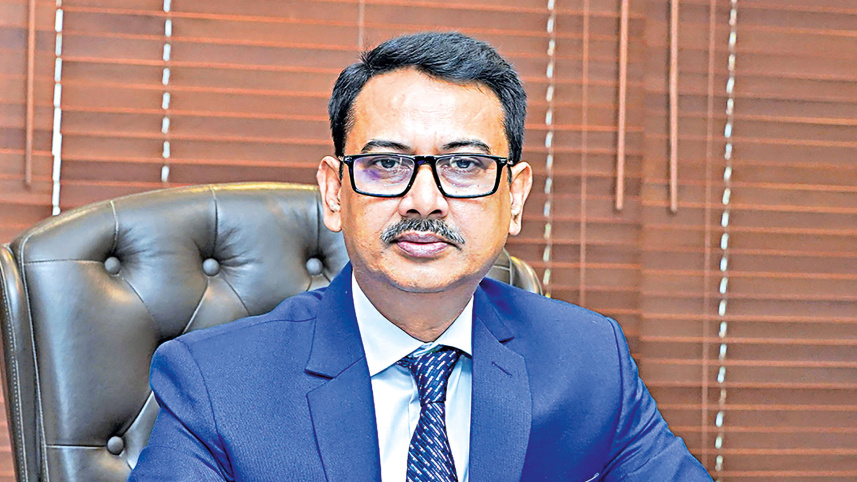
Financial institutions must judge rural entrepreneurs on skill and business capacity rather than relying solely on conventional collateral.
Shimanto Bank PLC is leveraging cutting-edge digital platforms, internet banking, and Mobile Financial Services (MFS) to collapse rural credit processing times from weeks to minutes. Md. Nurul Azim, Managing Director & CEO of Shimanto Bank, highlights why banks must evaluate entrepreneurial skill over physical collateral, expand central bank credit guarantees, and invest in post-harvest logistics infrastructure.
The Daily Star (TDS): How has the agricultural financing landscape in Bangladesh evolved in recent years, and which emerging trends do you consider most significant?
Md. Nurul Azim: Agricultural finance is steadily moving beyond traditional crop lending toward value-chain financing. Key emerging trends include the rapid adoption of digital banking, climate-smart agricultural practices, and targeted funding for storage, processing, and marketing across the full seed-to-shelf journey.
TDS: What changes are you seeing in the financing needs across the agricultural value chain?
MNA: Needs are broader and more commercial. Farmers require seasonal working capital, while aggregators, traders, and processors need finance for procurement, heavy machinery, inventory storage, and transport. Banks must structure loans to match each participant’s actual cash-flow cycle.
TDS: How is Shimanto Bank adapting its agricultural finance products to serve activities beyond crop production?
MNA: We treat agriculture as a complete value chain, extending support to crops, fisheries, livestock, processing, storage, and commercial distribution. Every facility is custom-structured around the borrower’s operational model, cash flow, and repayment capability.
TDS: What are the principal barriers to formal credit, and how can financial institutions address them responsibly?
MNA: Major obstacles include sparse financial documentation, informal cash transactions, insufficient collateral, and limited physical branch access. Extending field-level relationship banking and digitizing the end-to-end credit workflow offer the most effective solutions.
TDS: How are agent banking, digital platforms, and new credit assessment methods changing agricultural finance?
MNA: Agent banking delivers services directly to rural doorsteps. Internet banking and MFS reduce transaction turnaround times from weeks to minutes, while digital loan processing platforms are revolutionizing the total rural credit ecosystem.
TDS: How should financing models evolve to address climate and market risks?
MNA: Financing must emphasize climate-smart farming technologies, crop diversification, and innovative digital credit assessment. Tech-driven partnerships across selling and collection channels help manage market volatility effectively.
TDS: What more can financial institutions do to support women, young agripreneurs, and small enterprises?
MNA: Financial institutions must judge entrepreneurs on skill and business capacity rather than conventional collateral. Providing collateral-free soft loans, leveraging central bank refinance schemes, and sponsoring startup initiatives will boost young and women-led ventures.
TDS: What policy support, institutional changes, or partnerships are necessary for sustainable agricultural finance?
MNA: We need three crucial structural elements: expanding Bangladesh Bank’s Credit Guarantee Scheme (CGS) to absorb high-risk agri-portfolios, deepening bank-fintech collaborations, and building robust transportation, preservation, and local/export market infrastructure.
 For all latest news, follow The Daily Star's Google News channel.
Comments